
|
Getting your Trinity Audio player ready...
|
Karla Guity and her family pay just $1,800 a month for a three-bedroom house with a yard in Shoreline, Washington, just north of Seattle. The modest rent meant she did not have to work when her two daughters were young. She loves the neighborhood and the local schools.
She also worries she will never be able to leave.
Although Guity, 33, and her husband want to own their own home in the area, buying would be too much of a financial stretch as long as mortgage rates remained high. The possibility that a monthly mortgage payment would exceed $6,000 was enough to convince her that her family would stay renters for much longer than she had once thought.

“We’re depending on the graces of the landlord,” she said.
Higher mortgage rates are compelling aspiring homeowners across the country to continue renting, tightening competition for rentals and putting upward pressure on rents for the first time in years. According to private-sector data from real estate sites including Zillow and Apartment List, rents have steadied in recent months after a prolonged softening driven by a glut in new apartment buildings that sprouted up after the pandemic. Government data also shows sturdier rent growth.
The upswing in rents could pose a challenge for the Federal Reserve in its fight against persistent price increases. Though the Fed is expected to hold rates steady at its meeting Wednesday, investors anticipate the central bank will raise borrowing costs once more before year-end, which would keep mortgage rates elevated.
“We’re not in deceleration world anymore, probably not going to get a lot of disinflationary pressures from rents,” said Jonathan Millar, senior U.S. economist at Barclays. “If anything, the risks are that we may be going the other direction.”
The emerging signs of strength in the rental market follow a roller coaster of a period. During the depths of the pandemic, housing demand soared, fueled by a desire for more space, the ability to work from home and swelling savings. Without the supply to match, both home prices and rents skyrocketed in much of the country.
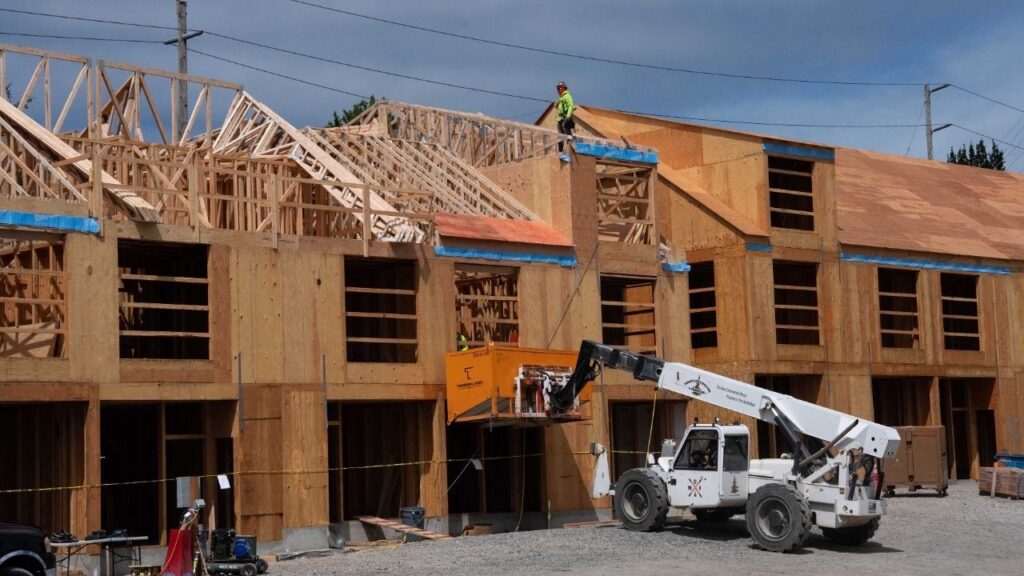
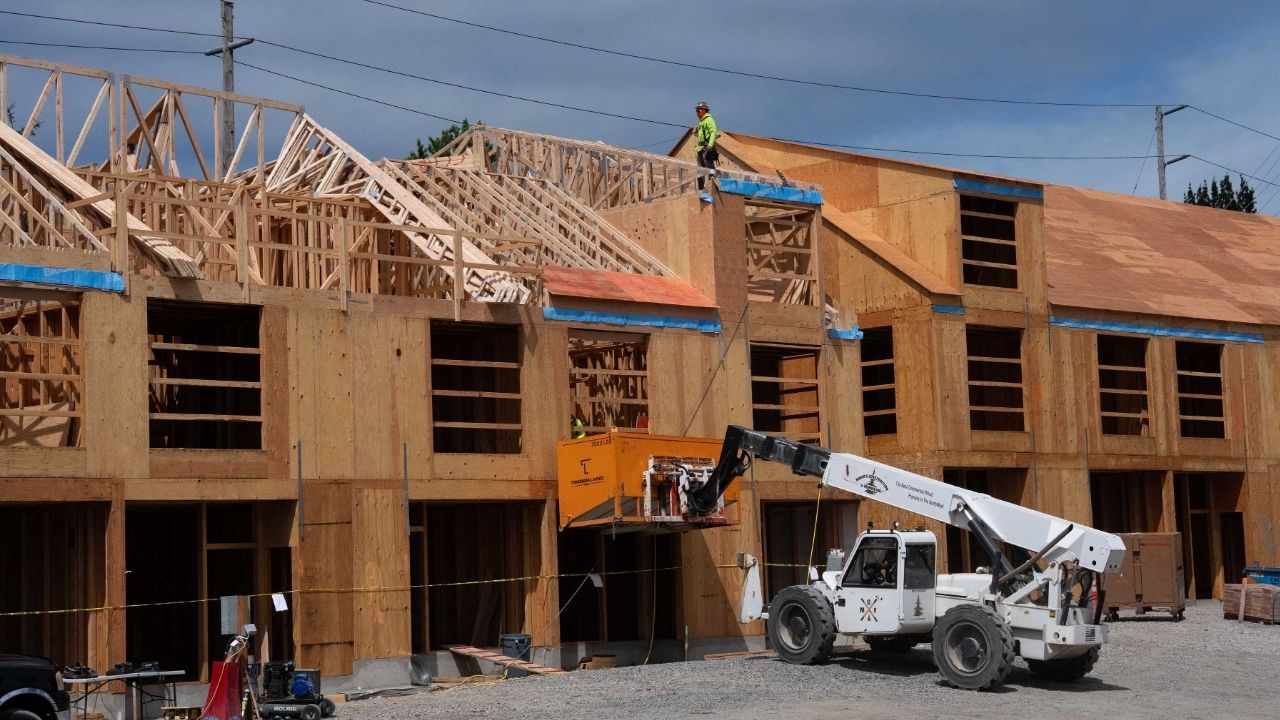
That demand for housing, coupled with rock-bottom interest rates, encouraged residential builders to flood growing cities, especially in the Sun Belt, with new rental properties. The mushrooming housing stock, along with generous incentives to attract renters, decreased landlords’ pricing power and compelled them to slash rents rapidly in many big cities nationwide. Rents in cities including Austin, Texas, and Phoenix plummeted in the years after the pandemic.
Then rising interest rates starting in 2022 made it more expensive to finance large construction projects, which slowed the building frenzy. Tariffs and supply chain troubles have pushed up material costs, and a labor shortage, exacerbated by President Donald Trump’s immigration policy, has also weighed on construction. Higher mortgage rates and lofty home prices are making homebuying increasingly inaccessible for a vast number of people. Homeowners who secured ultralow rates during the depths of the pandemic are reluctant to sell, further slowing the housing market.
At the same time, the labor market, which has been characterized by relatively few layoffs and a low unemployment rate, is allowing many workers to continue spending.
The result is that fewer new rental units are becoming available just as more people are clamoring for them. National rents rose 2.7% in September, according to the Zillow Observed Rent Index, compared with 2% a year earlier.
“Higher mortgage rates put pressure on the rental market not only from renters who are kind of stuck in there creating that demand,” said Molly Boesel, senior principal economist at Cotality, a housing market data provider. “But you also have that making it more difficult for builders to finance new apartments, so you could see a drastic slowdown in supply on the multifamily side.”
Most private rent indexes track new leases, which tend to adjust more quickly to market conditions. The rush of new apartment buildings in recent years, many of which reduced rents to lure tenants, caused rents in a number of cities to drop. Renters who renewed their leases continued to see their rents go up.
Lance Swank, CEO of the Sterling Group, a multifamily builder in Mishawaka, Indiana, said his company had taken advantage of low interest rates to ramp up construction. When it became clear that a wave of new rental developments was about to inundate the market, his company decided to scale back.
“We became much more selective,” he said.
It is not clear how much momentum the rental market is gaining. Yet the fact that it appears to be on slightly stronger footing at all has defied some economic projections.
Most notably, Stephen Miran, who served briefly as a Fed governor, said in a speech last year that he expected that the Labor Department’s measure of rent inflation would fall below 1.5% in 2027, from its level at the time of about 3.5%. One reason he cited was stricter immigration policy, which he believed would reduce the demand pressure on rents.
“One might characterize this view on rental inflation as optimistic,” he said in the speech. “However, I believe forecasters have underappreciated the significant impact of immigration policy on rent inflation — both on the way up and, now, on the way down.”
Complicating the picture for the Fed is a lag between moves in rental market data and government data. Typically, the consumer price index, released by the Bureau of Labor Statistics, takes time to catch up to market rents, partly because the government surveys any given rental property only once every six months. That means that if rent goes up the month after a survey, it will take another five months for it to show up in the data.
At the moment, however, rent inflation appears to be moving in step with market rents. One possibility for the alignment is that landlords are eager to raise rents, said Mark Franceski, chief strategist at Middleburg, a developer of rental housing.
“Whether growth is flattening or accelerating, they seem to be moving in the same direction,” he said. “This is becoming less of a renters’ market and more of a landlords’ market.”
Forecasters broadly believe that the factors pressuring rents upward are not going away in the near term. The slowdown in residential building will limit housing availability. Mortgage rates, which are unlikely to fall substantially any time soon barring a recession, will keep pushing more people into the rental market.
“In theory, higher rates make it more restrictive: You slow growth, that lowers inflation,” said Chris Salviati, chief economist at Apartment List.
“There is the counterargument that because you’ve got higher rates, you’re going to have less building, and then you’re going to have less supply,” he added. “And that will increase the pressure on shelter rents and make inflation worse.”
—
This article originally appeared in The New York Times.
By Sydney Ember/Ruth Fremson
c. 2026 The New York Times Company